Charter schools don’t get free buildings the way traditional public schools do. You have to find, finance, and manage a facility yourself, on top of running a school. This guide walks through your financing options, the planning mistakes that can trip up leadership teams, and what lenders look for before approving a loan.
Why Is Charter School Facility Financing So Difficult?
District schools get taxpayer-funded buildings. You don’t. Your school competes in the private real estate market and has to qualify for commercial financing, the same as any small business would. That means balancing your program’s needs, how the building looks to families touring it, and what you can actually afford, all while running a school day-to-day.
What Planning Mistakes Should You Avoid?
Two mistakes derail more facilities projects than anything else: an unclear budget and a rushed timeline.
Before you look at a single property, know your numbers. Calculate your current monthly operating costs, project enrollment and revenue growth, and figure out the maximum facility payment you can carry without touching your cash reserves or cutting academic programs. Build in room for moving costs, renovations, and new equipment too.
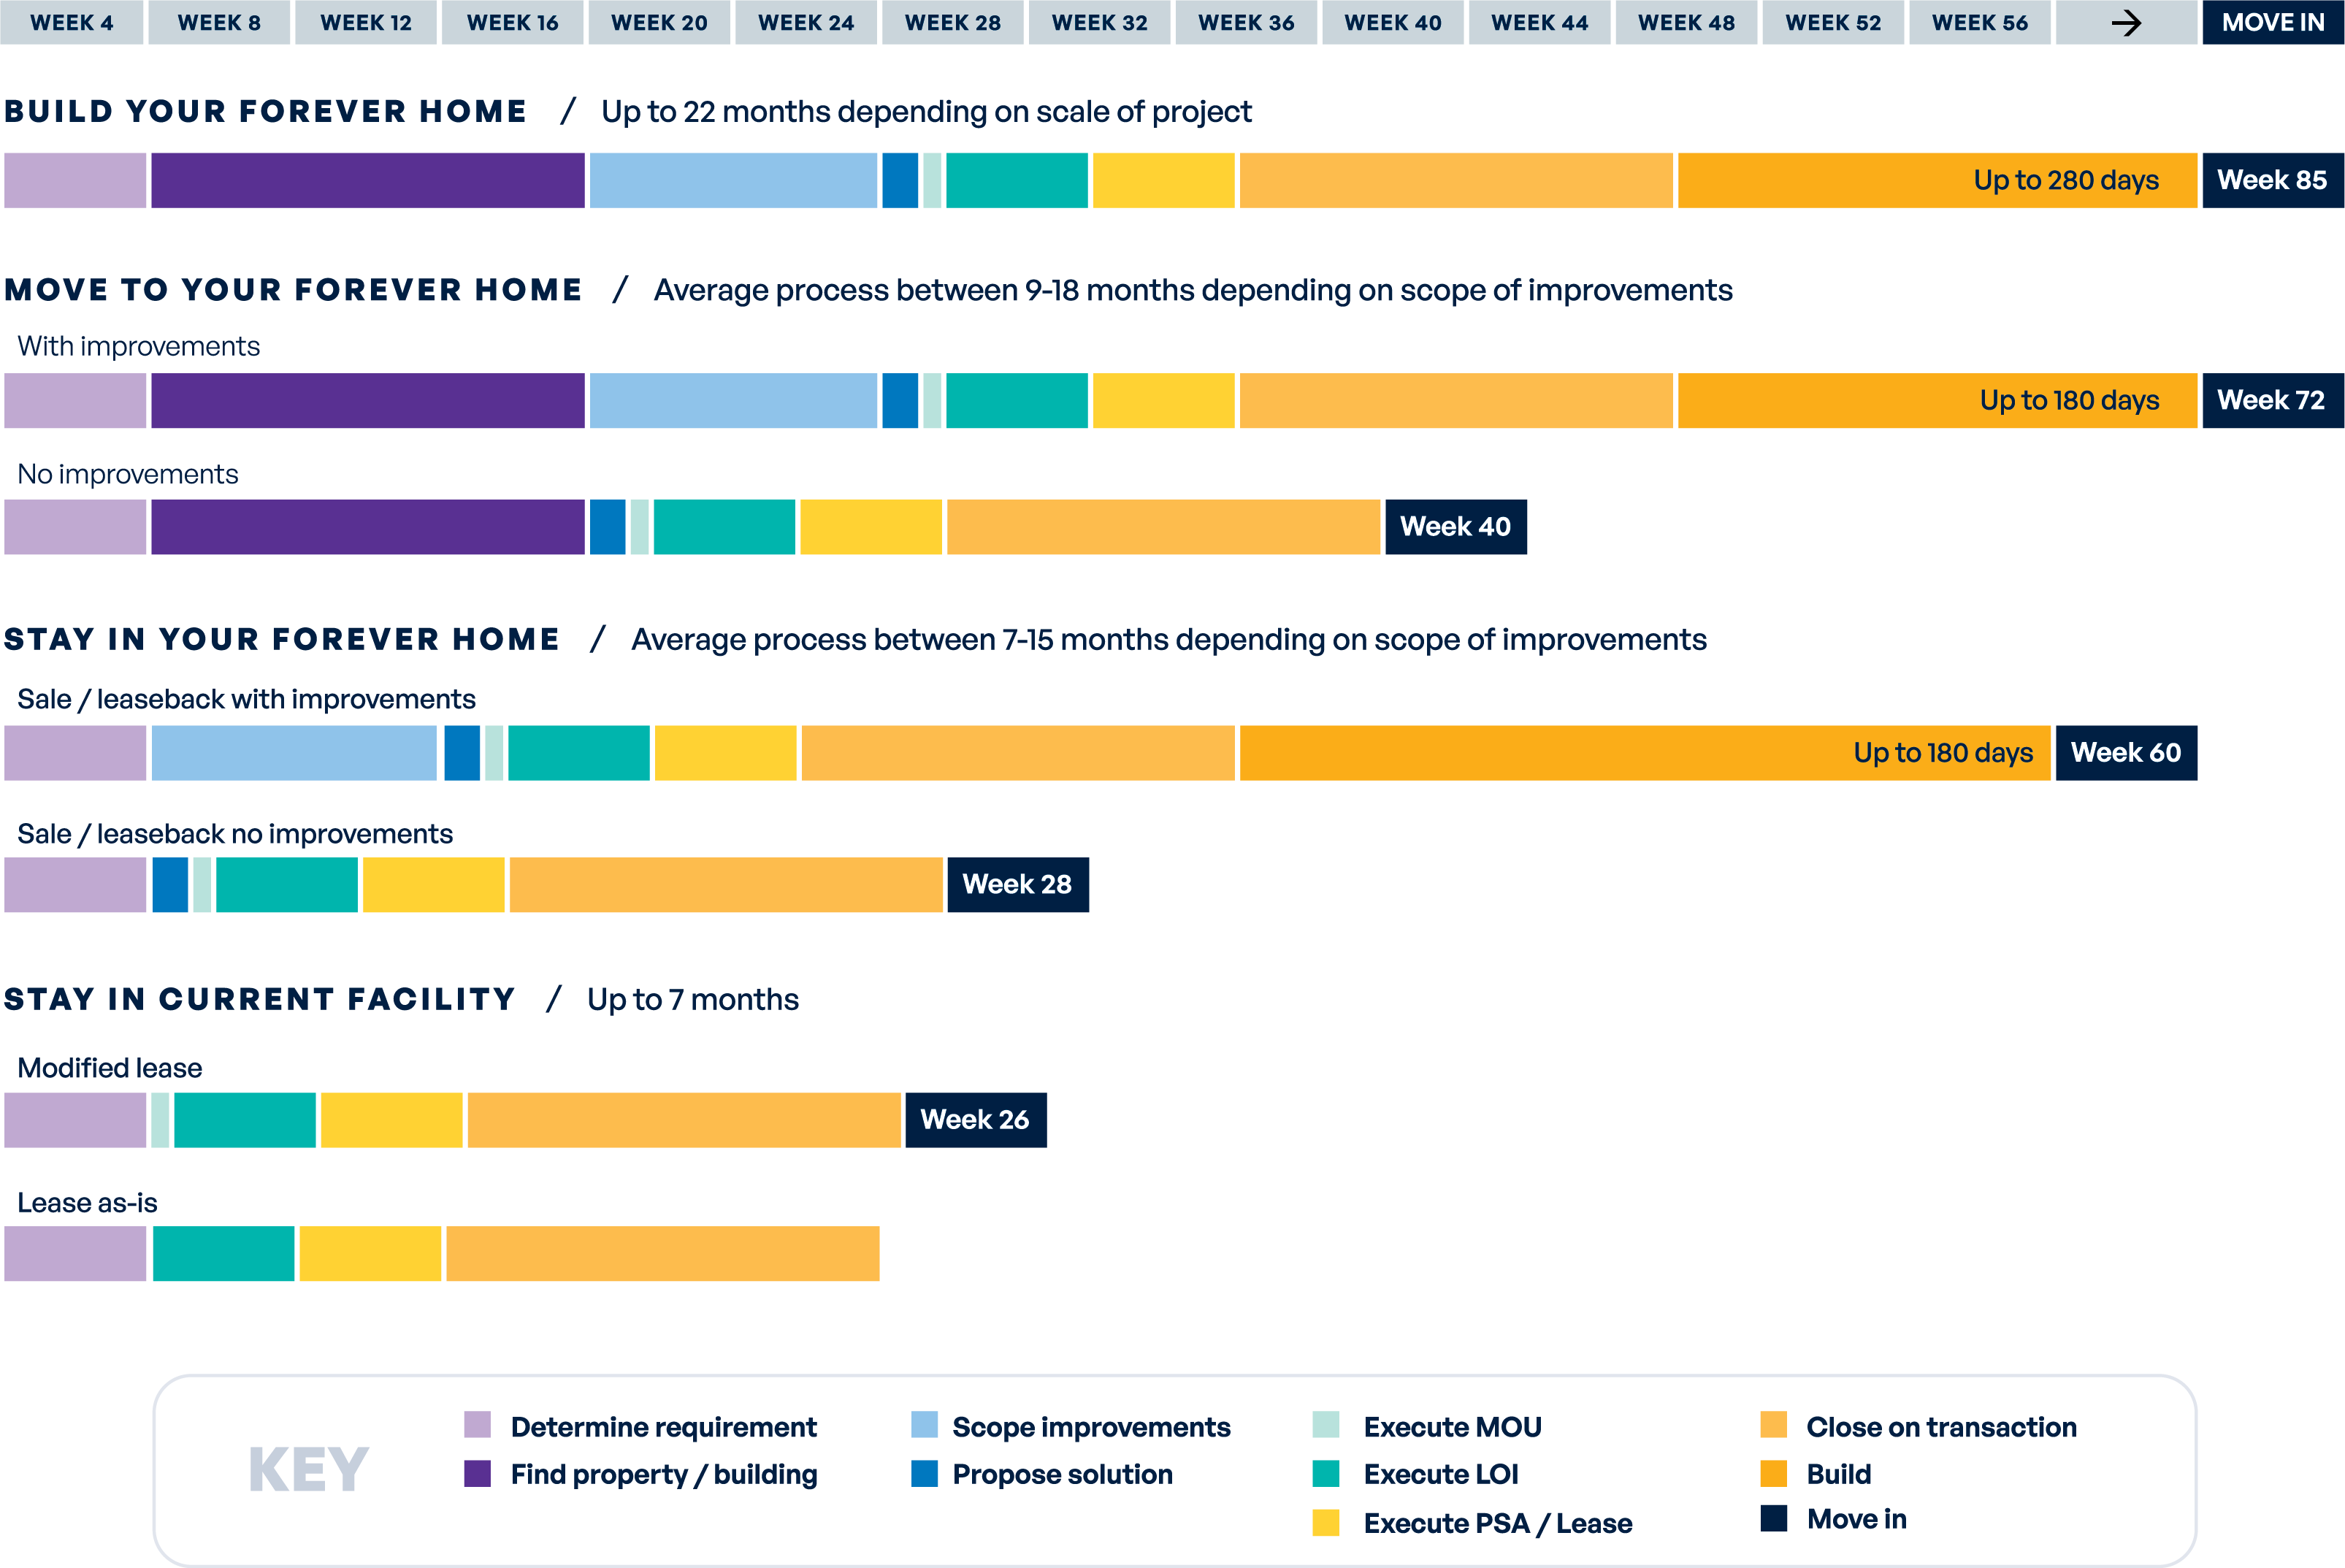
Then give yourself time. Facility projects take at least 12 months from planning to move-in, and that’s for straightforward ones. Legal approvals, construction delays, and staff and student transitions all take longer than leadership teams expect. Schools that compress the timeline end up making rushed decisions and absorbing cost overruns.
How Do You Balance Program Needs, Appearance, and Budget?
Every facility decision comes down to three things pulling against each other: what your educational program needs, how the building presents to prospective families, and what you can afford.
Your program needs are non-negotiable. A STEM-focused school needs lab space. An arts program needs a performance space with real acoustics. If you serve students with disabilities, you need accommodations built in from the start.
Appearance matters more than most school leaders expect, because it drives enrollment, and enrollment drives the revenue that funds everything else. Families notice the building on their first tour, and they compare it to other options in your area.
Budget is what keeps the first two honest. A facility that fits your mission but breaks your budget isn’t a win. Lenders will look at your cash reserves, your operating revenue, your charter term, and any grants or subsidies you have lined up before they tell you what you can actually borrow.
What Are Your Financing Options?
Most charter schools choose from four paths, and each fits a different stage and size of school.
Paying cash means no debt and no underwriting, but it ties up reserves you could otherwise put into classrooms, and most schools don’t have that kind of cash on hand. It mainly works for well-established schools with strong reserves taking on a smaller project.
Bank financing typically requires 20 to 40 percent equity upfront, plus a strong financial track record and enrollment history. It costs less than bond financing and builds equity over time, which makes it a fit for established schools with cash on hand tackling projects of $7 million or more.
Bond financing offers fixed, predictable costs over a 30-year term and doesn’t require a large upfront payment, but it comes with a lengthy underwriting process, hundreds of thousands of dollars in legal fees, and a $10 million minimum. Only about 12 percent of charter schools nationwide go this route. It suits large, stable schools settling into a permanent home with no more expansion ahead.
A long-term lease, typically 20 to 40 years, gets you a predictable monthly payment and low upfront cost without bond- or bank-level underwriting. You won’t build equity, and rent may climb over the term, but a lease works for schools at nearly any stage that want control over their space without a heavy capital commitment.
What Do Lenders Look for Before Approving Financing?
Four things carry the most weight.
Enrollment stability comes first. Lenders want to see your enrollment holding steady or growing against your charter capacity, a real waiting list, and a market that isn’t already saturated with charter options.
Leadership experience comes next. A track record of running schools well, a board with real financial and governance expertise, and evidence you’ve planned for succession all strengthen your case.
Financial management is where the numbers get scrutinized directly. Lenders want your facility costs under 20 percent of operating revenue, healthy debt service coverage, multiple years of audited financial statements, and cash reserves that hold up under stress.
Governance and your relationship with your authorizer round it out. A strong renewal history, a clean compliance record, and consistent communication with your authorizer all signal that you’re a safe bet.
How Do You Get Started?
Start with the budget analysis, not the property search. Once you know what you can afford, define the space your program actually needs and look at what’s available in your area at that price point. Build your cash position in the meantime, and bring in people who do this for a living: a commercial real estate broker who knows schools, a lender or advisor familiar with charter financing, and legal counsel who’s handled these deals before.
Grow Schools’ Money to Buy Your School program works with charter schools on exactly this kind of financing, from a first permanent building to a major expansion. Reach out and we’ll walk through what fits your school.
How long does charter school facilities financing take?
Plan on at least 12 months from the start of planning to move-in. That covers legal and regulatory approvals, any construction or renovation work, and the staff and student transition, and most of those steps take longer than schools expect.
How much of my operating budget should go toward facility costs?
Keep facility costs under 20 percent of your operating revenue. Lenders use this as a key threshold when they evaluate your loan application, and staying under it protects the budget you need for academic programs.
What percentage of charter schools use bond financing?
About 12 percent. Bond financing has a $10 million minimum project size and a lengthy underwriting process, which puts it out of reach for most schools. The other 88 percent finance facilities through cash, bank loans, or long-term leases.
How much equity do I need for bank financing?
Most banks want 20 to 40 percent equity upfront, along with a strong financial track record and stable enrollment history. This route generally suits established schools taking on projects of $7 million or more.
What’s the minimum project size for bond financing?
$10 million. Bond financing also comes with hundreds of thousands of dollars in legal fees and a long approval process, so it’s built for large, stable schools settling into a permanent facility with no further expansion planned.
What do lenders look at before approving a charter school facility loan?
Four things: enrollment stability, leadership experience, financial management, and governance. Lenders want steady or growing enrollment, a proven leadership team, facility costs under 20 percent of revenue, and a clean compliance record with your authorizer.
What’s the best financing option for a school’s first permanent building?
A long-term lease is usually the best fit for a first building. It requires minimal upfront cash, gives you a predictable monthly payment, and skips the heavy underwriting that bank and bond financing require, which makes it accessible to schools at any stage.
Want to share?